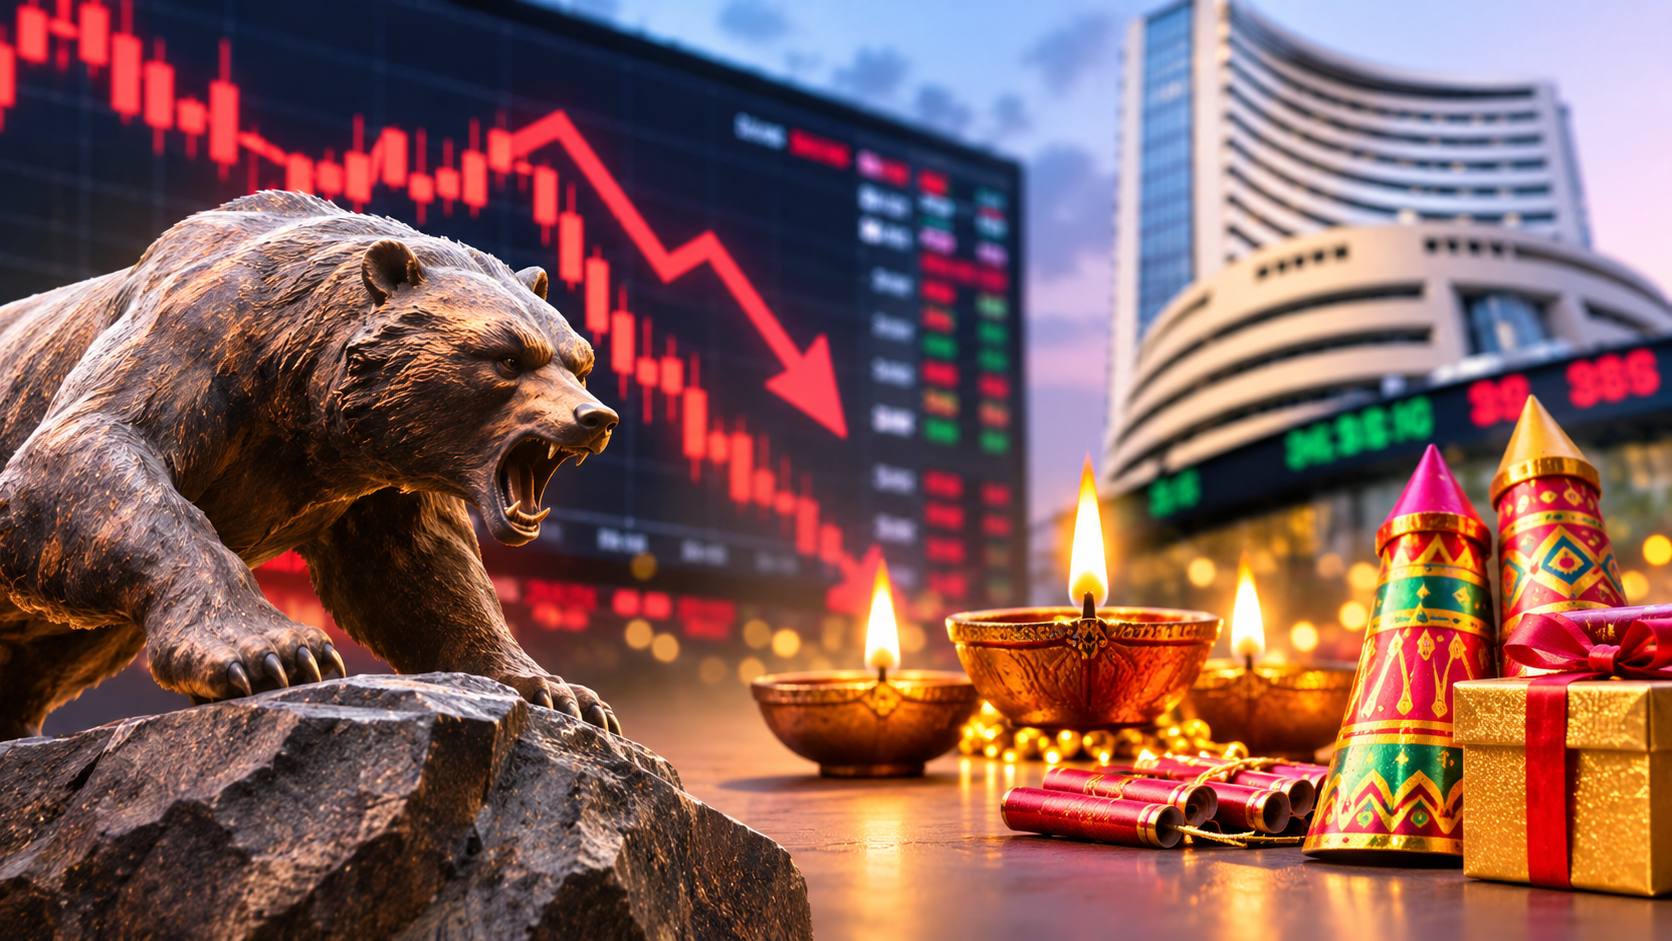
The festive season is here, and at the BSE, Deepavali comes with a tradition of its own. Brokers gather on the trading floor for Lakshmi Puja, followed by the special Muhurat trading session that marks the beginning of the new accounting year.
There is usually plenty of cheer around. Clients call their brokers to execute their first trade of the new year, hoping to begin on an auspicious note. This year, however, the mood could be rather different.
The Indian stock market has had a dismal run over the past year, with the Nifty 50 down 9.5%. Against that backdrop, there is not much room for optimism as we head into the new year.
In my opinion, there are four important and crucial factors right now.
1) Global Risks, Indian Impact: The Russia-Ukraine war is said to be the largest conventional war in Europe since World War II; with no resolution in sight. India has been hit by the ongoing wars through higher fuel import costs, adding to inflation i.e a rise in the prices we pay for everyday goods and services. The pressure has come not only from higher crude oil prices, but also from disruptions to global supply chains, which have made several goods more expensive to produce and transport. Added to this is the Iran war and the changing tariff policies of the Trump administration on India.
First and foremost, these events are not in our hands to control. But they are affecting India directly because of our higher dependency on foreign crude oil.
When do we expect these concerns to recede? It is anybody’s guess! What is clear, however, is that the inevitable task will fall on the Indian government to manage the fuel situation and cushion the economy from the impact.
2) Foreign Investors Pull Back: FII outflows from Indian equities have been sharp, at $56 billion over the past two calendar years, offsetting their cumulative inflows since CY2019 and also pushing decade-long cumulative flows close to zero, according to a report published by Motilal Oswal Research.
According to the data, FIIs have sold Indian equities worth $25.6 billion in CY2026 so far, with flows remaining extremely volatile. In the first nine months, FIIs bought shares in just three months — February ($1.7 billion), July ($2.5 billion) and August ($2.4 billion).
What could bring FIIs back to India? Steady earnings growth from our companies, a stable rupee and predictable tax policies. The increase in capital gains tax to 20% for short-term gains and 12.5% for long-term gains has made other emerging markets more attractive.
This has also partly caused the Indian rupee to weaken by over 7% this year, making it one of the worst-performing currencies in the world.
The FII selling was somewhat balanced by domestic Mutual Fund (MF) inflows, but that also seems to be slowing down due to the non-performance of the market. If both foreign and domestic investors become cautious at the same time, the market loses an important source of support.
The government, therefore, needs to focus on taxation policies in the upcoming Budget and restore the confidence of both FIIs and domestic investors.
3) Rates, Rupee and Rising Prices: Since these go hand in hand, the near-term expectation is a 25-basis-point hike before Deepavali and most likely another round in the New Year. If this happens, there is a likelihood of shrinkage in corporate earnings due to higher borrowing costs.
We expect inflation to rise, so the key will be managing inflation and avoiding too many upward revisions in interest rates by the RBI. Adding to the pressure is a weaker rupee, which makes imports such as crude oil more expensive. The Indian currency has depreciated by 7% in this calendar year, compounding the problem.
4) Cheap, Expensive or Just Right?: The most popular argument for a market rebound during bearish phases is cheap or “reasonable valuations”.
What makes the market cheap or expensive? More than the price-to-earnings (PE) ratio of the index, it is mostly sentiment, which can turn either way, even with a constant PE! Simply put, the PE ratio tells us how much investors are willing to pay for every rupee a company earns. We are at less than 19 times, which signifies “fair valuation”. But it is earnings growth that matters. Higher PE can be justified when the growth momentum is persisting. In other words, investors may be willing to pay a higher price for stocks if companies continue to grow their profits. So, it has to be seen whether earnings do improve.
However, at the end of the day, in predicting stock market performance, everyone has a 50% chance of being right! So we make the predictions, broadly based on more or less a consensus method. The market always has a way of tricking us into believing that the outlook is bleak. Just when you decide to cancel all your Systematic Investment Plans (SIPs) and start a recurring deposit (RD), or sell your carefully built equity portfolio to “stay in cash” during difficult times, the market can take us by surprise. Staying in cash simply means keeping money away from investments while waiting for conditions to improve. Normally, rebounds can be sharp and furious, benefiting investors.
To sum it up geopolitical tensions, FII outflows, inflation, interest rates and valuations may continue to keep markets volatile in the near term. But markets have weathered difficult periods before, and short-term uncertainty should not distract investors from their long-term goals.
Investing is a game of patience. Don't react to every event taking place globally. Stay invested to reap long-term benefits!
முந்தைய செய்தி
India’s Nasdaq Moment: From Reverse Flips to Global Shopping Sprees
அடுத்த செய்தி
Health Insurance: The Cover and the Catch