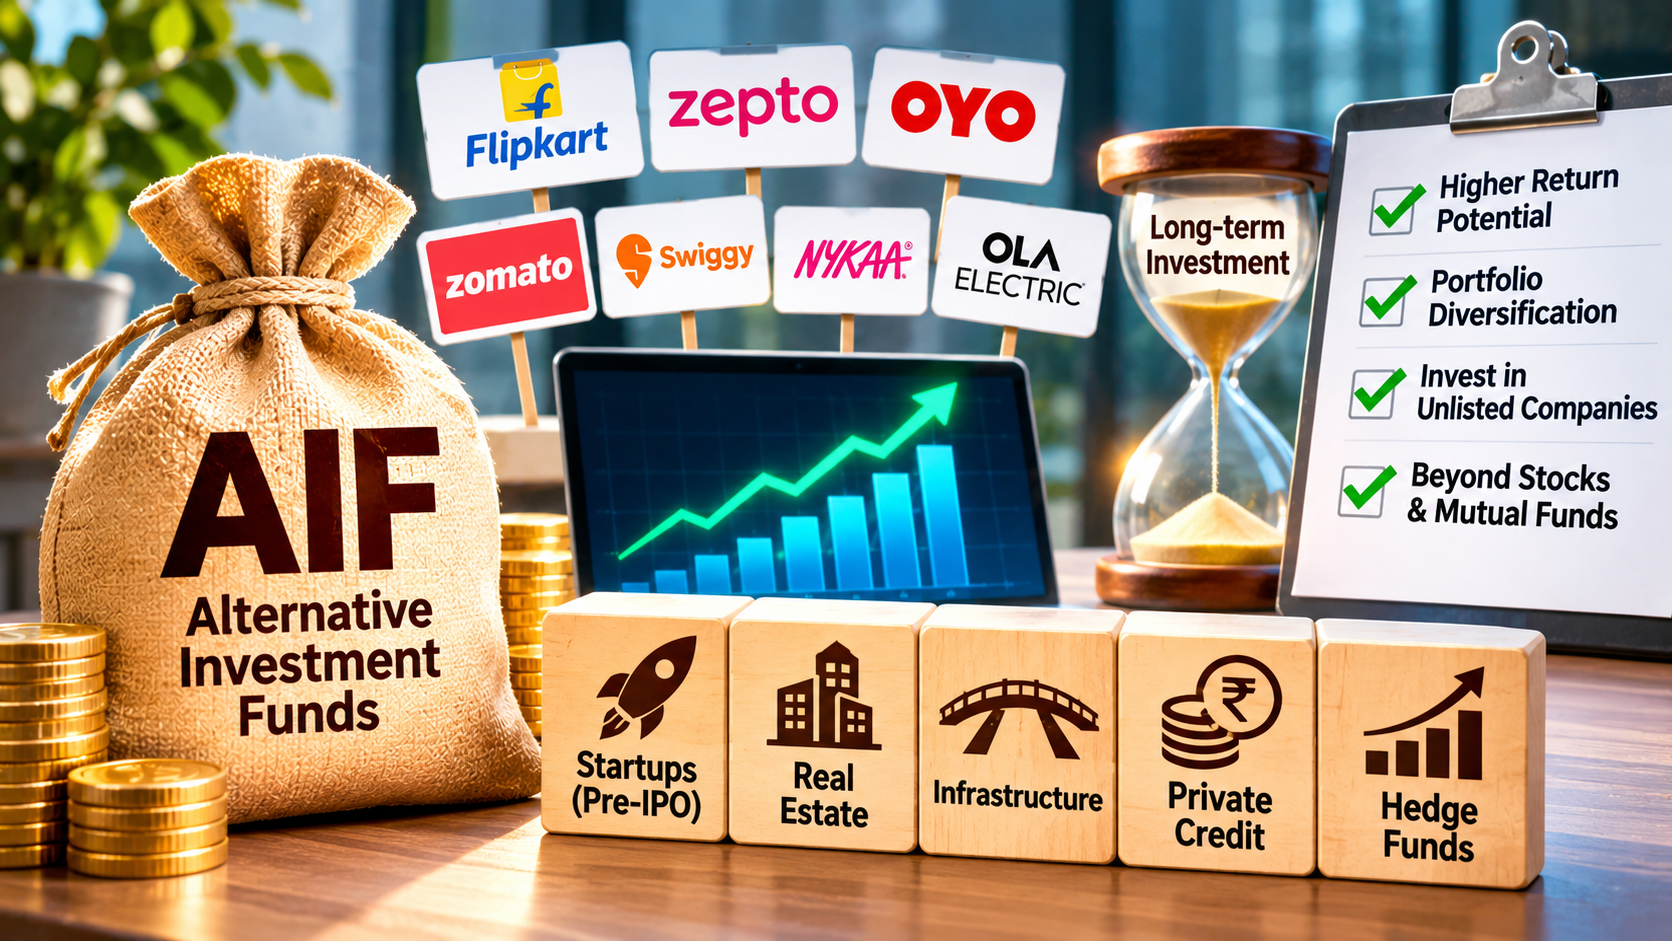
Have you ever wished you could invest in India's biggest startups before they hit the stock market? Imagine getting a chance to invest in companies such as Flipkart, Zepto or OYO while they are still privately held. Or imagine having invested in Zomato, Swiggy, Nykaa or Ola Electric years before their initial public offerings (IPOs).
For most ordinary investors, such opportunities have traditionally been out of reach. By the time a promising startup lists on the stock exchange, much of its early growth may already have taken place, with venture capital and private equity investors among those benefiting from its rise.
But what if you could invest in such companies before they go public?
That's where Alternative Investment Funds (AIFs) come in.
AIFs allow eligible investors to pool their money and invest in opportunities beyond traditional stocks, bonds and mutual funds. Some invest in startups and privately held companies, while others focus on private credit, real estate, infrastructure or sophisticated trading strategies.
Regulated by the Securities and Exchange Board of India (SEBI), these funds are divided into three categories based on their investment strategies.
However, there is a catch. The minimum investment is generally ₹1 crore, making AIFs an option primarily for wealthy investors. And unlike listed shares, these investments can be difficult to sell, sometimes requiring investors to lock away their money for several years.
Three ways to invest beyond the stock market
Broadly speaking, alternative investments can be divided into three categories, each behaving differently from traditional listed investments.
The first is private capital, where money goes into private companies and loans. These investments are usually held for longer periods, with fund managers working closely with the management of the companies they invest in. Private equity, venture capital and private credit come under this category.
The second is real assets. Think of properties, infrastructure projects and natural resources. These investments can generate income through rent, toll collections or long-term contracts, apart from an increase in the value of the underlying assets.
The third category is hedge and structured investments. These funds use flexible strategies and specially designed financial instruments, often including derivatives, to generate profits in both rising and falling markets. Market-linked debentures, hedge funds and asset-backed securities come under this category.
But before we get into the positives, let's look at the two main drawbacks.
The first as we mentioned earlier is the high entry barrier. The minimum investment in an AIF is ₹1 crore.
The second is low liquidity. Unlike listed shares or mutual funds, AIF investments cannot always be sold or redeemed easily because of their very structure.
Why should you consider AIFs?
Despite these shortcomings, when should an investor start looking at alternative investments?
Once you have allocated enough money to liquid investments such as fixed deposits, bonds, equities and mutual funds, you can consider AIFs for their potential to deliver higher returns for similar risks.
So, what makes AIFs different from traditional investments?
For starters, their returns can be independent of stock market indices. They also offer broader diversification, giving your portfolio an edge over traditional investments.
Real estate funds offer higher returns from property without physical ownership, while private credit funds can generate fixed-income returns substantially higher than average bank FD rates.
But perhaps the biggest attraction, and also the highest-risk, highest-return opportunity, is the possibility of exponential growth by investing in companies before they list on the stock exchange.
This makes AIFs particularly suitable for high-net-worth individuals seeking long-term growth outside listed markets.
The Indian AIF industry has grown more than threefold in the past five years to approximately ₹17.5 trillion.
Are AIFs right for you?
How do you decide whether AIFs are suitable for you? There are a few green signals.
Are you looking for returns higher than bank FDs? Do you already have adequate exposure to traditional investments and are no longer building your core wealth? Are you comfortable with a longer investment horizon, including lock-in periods and limited liquidity? Do you already own multiple properties?
If so, AIFs may be worth considering.
But there are definite red flags, too. If you are new to investing, still building your core portfolio or might need the money soon, AIFs may not be suitable.
The same applies if you expect guaranteed returns or tend to panic and sell whenever markets fall.
How much should you invest?
So, what is the ideal AIF allocation?
That depends entirely on your risk profile, ability and willingness to take risks. Even then, it would be wise to restrict AIF exposure to about 1% to 20% of your overall portfolio, keeping in mind the illiquidity and high-risk characteristics.
And remember, long term really means long term here. Some AIF investments can run for 10 to 12 years.
So the prudent way to invest would be to match your requirements with the different AIF categories, understand the pros and cons, consult your auditor about taxation and only then decide where to invest.