A home is often the most expensive asset an individual builds over a lifetime. However, only 1% of Indian homes are insured. This is in stark contrast with developed countries. In the USA, around 95 per cent of homeowners have some form of home insurance, and in the UK, 70-75 per cent of homes are insured.
Home insurance in India is one of the most overlooked yet essential financial tools for safeguarding a household's wealth. While motor insurance is legally mandated and health insurance has gained significant traction, home insurance remains largely neglected by a vast majority of Indian homeowners.
Most home insurance policies are taken with a home loan. Banks often ask borrowers to obtain property insurance to safeguard against property damage, ensuring the loan amount is protected.
Is home insurance costly? No, not at all. The annual insurance premium for a house valued at Rs. 1 crore is about Rs. 1,000.
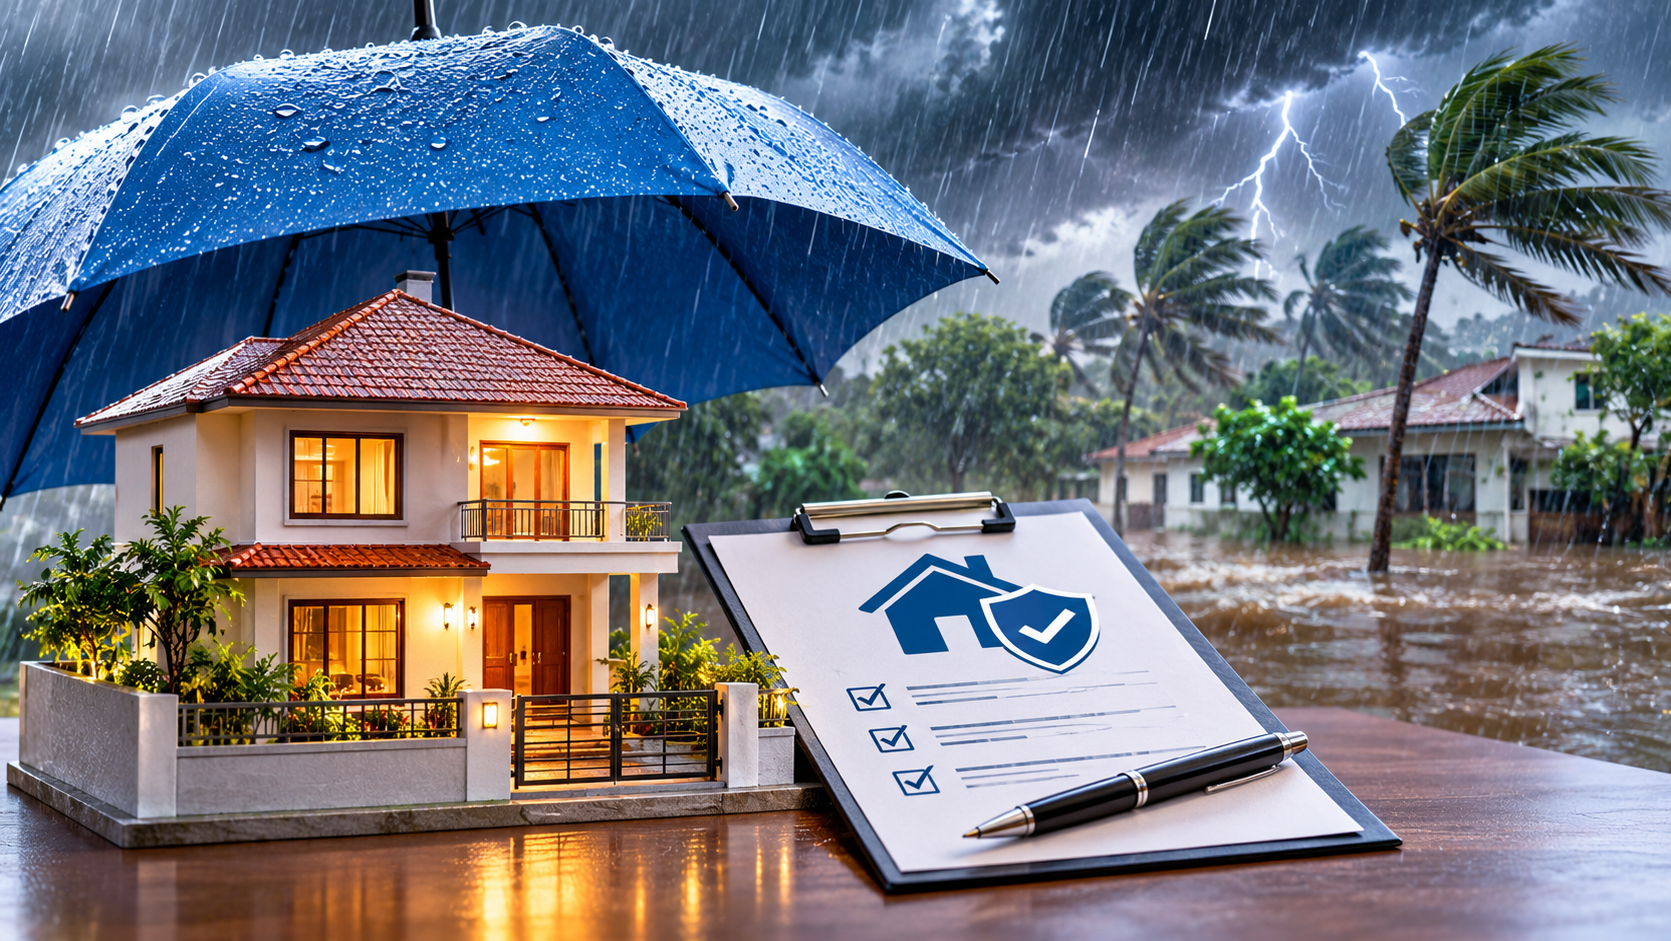
The standard insurance policy is the Bharat Griha Raksha policy, which the Insurance Regulatory and Development Authority of India (IRDAI) introduced. It covers fire and natural calamities such as earthquakes, volcanic eruptions, floods, typhoons, cyclones, hurricanes, tornadoes, tsunamis, landslides, and rockslides.
Beyond covering the physical structure of the building, the policy automatically covers home contents up to 20% of the total sum insured (up to a maximum of ₹10 lakh) without requiring the policyholder to submit a detailed, itemised list of every household item. This is particularly beneficial during natural calamities, where precious appliances, furniture, and personal belongings are often destroyed along with the building.
The Bharat Griha Raksha policy has comprehensive, built-in coverage for natural catastrophes. Unlike older insurance products that required policyholders to pay extra premiums for specific add-ons, this policy automatically covers a broad spectrum of natural disasters.
It provides protection against fires, earthquakes, volcanic eruptions, floods, typhoons, cyclones, hurricanes, tornadoes, tsunamis, landslides, and rockslides. Whether a home is structurally damaged by a severe earthquake in Delhi or submerged under floodwaters in Bengaluru, Bharat Griha Raksha ensures that the homeowner is not left to bear the exorbitant costs of rebuilding alone.
The under-insurance clause, which used to penalise policyholders if their property was insured for less than its actual market value, has been completely eliminated under Bharat Griha Raksha. If a partial loss occurs, the insurer pays the actual cost of the damage up to the sum insured.
While calculating the sum insured (the value for which insurance is taken), care is advised. It may be calculated by multiplying the property's total built-up area in square feet by the current local cost of construction per square foot, entirely excluding the land value. This ensures adequate protection in case of an unfortunate loss.
Climate change has increased natural calamities. From the cyclone-prone coastal belts of Odisha and Gujarat to the seismically active Himalayan regions and the floodplains of Bihar and Kerala, disaster risks are a constant reality.
The risk, however, is not confined to major weather events. Even ordinary spells of rain can expose homes in India’s largest cities to inundation. In Chennai, Mumbai, Bengaluru and Delhi, poorly maintained drains, encroached waterways, concretised open spaces and inadequate storm-water infrastructure often turn a few hours of heavy rain into waterlogged streets. Water enters ground-floor homes, damages electrical wiring, furniture, appliances, documents and stored belongings, and leaves behind dampness and structural stress long after the water recedes. For many households, the loss begins not with a cyclone or a cloudburst, but with rainwater entering a home because the road outside is flooded.
The recent floods in Nepal offered another reminder of how interconnected the region’s weather risks have become. While the worst damage occurred in Nepal, heavy rain and swollen rivers affected several areas in northern and eastern India as well. Such events show that flood risk does not respect administrative boundaries: excessive rainfall upstream can translate into inundation, displacement and property damage downstream. Homeowners therefore need to view insurance not as protection against a rare catastrophe, but as a practical safeguard against increasingly frequent water-related losses.
India is among the most disaster-prone countries in the world. Over 58% of India’s landmass is prone to earthquakes, over 12% of its land is prone to floods and river erosion, 5,700 km of its 7,517 km-long coastline is prone to cyclones and tsunamis, and its hilly areas are at risk from landslides and avalanches.
Insurance penetration in India stands at a stagnant 3.7% of GDP, significantly below the global average of 7.3%, according to the latest data from the Insurance Regulatory and Development Authority of India (IRDAI). Life insurance penetration is at 2.7%, while non-life (general) insurance remains stuck at a low 1.0%. The government has initiated several policy reforms, including the Sabka Bima, Sabki Suraksha Act, which raised the Foreign Direct Investment (FDI) limit to 100%. This, along with the goal of “Insurance for All by 2047,” could see a significant expansion of insurance coverage.
It is never too late to take home insurance.
As Ralph Waldo Emerson said, “A house is made with walls and beams; a home is built with love and dreams.”
முந்தைய செய்தி
AI: Neither Magic Nor Hype — Five Myths to Retire
அடுத்த செய்தி
When a $9 Billion Dream Collapsed: The Theranos Story Every Investor Must Remember